What is CSRD reporting?
CSRD reporting refers to the mandatory sustainability reporting required of certain companies under the Corporate Sustainability Reporting Directive (CSRD) and the associated European Sustainability Reporting Standards (ESRS). Reports cover not only environmental and climate issues but also social issues, human rights, governance, risks, opportunities, goals, and the company’s impact on people and the environment.
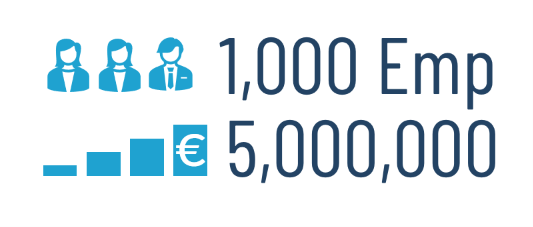
For Austrian companies, the key question in 2026 will no longer be solely whether a company is “large” or publicly traded. Of particular importance are the current scope of application under Directive (EU) 2026/470 and its implementation in Austria through the Sustainability Reporting Act ( NaBeG, Federal Law Gazette I No. 6/2026 ). In simple terms, the direct reporting requirement will apply in the future primarily to large companies with more than 1,000 employees and net revenue exceeding 450 million euros. Separate requirements apply to certain third-country scenarios.
The original thresholds and deadlines for the implementation of the CSRD Directive (EU) 2022/2464 had been amended by the Omnibus I Package (“Stop-the-clock”).
Companies outside the mandatory scope of application may still need ESG data—for example, from banks, investors, customers, or business partners subject to reporting requirements. For smaller companies, therefore, the EU’s sustainability reporting standard based on voluntary adoption—known as the Voluntary Standard or VS (formerly VSME)—is relevant.
Who is required to file a CSRD report in Austria?
Major Austrian companies
Based on the current status of implementation, large corporations in particular are affected if they exceed both of the following thresholds:
- More than 1,000 employees during the fiscal year and
- More than 450 million euros in net sales.
The thresholds should be considered a general guideline. Additional or different rules apply to corporate groups, parent companies, financial institutions, certain regulated entities, and companies conducting business in the EU through a non-EU parent company.
Austrian subsidiaries and branches of non-EU companies
Certain non-EU companies and their EU subsidiaries or branches are subject to specific reporting requirements. The audit must therefore take into account, among other things:
- Registered office and legal form of the corporate group,
- Sales within the EU,
- Revenue and operations of the Austrian unit,
- Existence of an EU subsidiary or branch office,
- Existing consolidated reporting.
Are publicly traded SMEs still automatically affected?
No. The previous understanding—that publicly traded companies with more than ten employees automatically fall within the scope of the CSRD—is no longer accurate under current law. Changes at the EU level and Austria’s implementation of the legislation have significantly narrowed the mandatory scope of application.
Are unlisted SMEs affected by the CSRD?
Unlisted SMEs are generally not directly subject to CSRD reporting requirements. However, they may still be required to disclose sustainability information if it is relevant to customers, banks, investors, insurance companies, or other business partners.
For such companies, a voluntary, proportionate sustainability report prepared in accordance with the relevant voluntary standard is often a more practical approach than a report prepared in accordance with the full ESRS.
What must be included in the CSRD report?
Sustainability reporting is prepared as part of the management report. Its purpose is to explain how sustainability issues affect the company and what impact the company has on people and the environment.
Typical report content includes:
What does “double materiality” mean?
Double materiality is the central approach to assessing and structuring sustainability reporting. A sustainability issue is relevant if it is material from at least one of the following two perspectives:
The materiality analysis therefore does more than just determine the level of detail in the report. It also serves as a foundation for strategy, risk management, data collection, and internal responsibilities.
Key terms
CSRD
CSRD is the EU directive that specifies which companies are required to report sustainability information and what basic requirements apply.
ESRS
ESRS are the European reporting standards that specify what information and metrics must be disclosed in the sustainability report.
NaBeG
NaBeG is the Austrian law that incorporates the relevant EU requirements into Austrian law and adapts national regulations in corporate law.
EU taxonomy
The EU taxonomy is a separate classification system for environmentally sustainable economic activities. Information on the taxonomy may be included in sustainability reporting, but it does not replace the CSRD report.
Does the CSRD report need to be audited?
Yes. The CSRD requires an external audit or assurance of sustainability reporting. Until further notice, the audit is generally conducted on a “limited assurance” basis. The specific procedures, the authorized auditors, and the applicable audit requirements are governed by applicable EU and Austrian law.
The CSRD remains relevant for SMEs as well
Even companies outside the immediate scope of the CSRD may be faced with ESG inquiries. Companies subject to reporting requirements need information from the value chain, among other sources, for their own reporting. But banks, investors, and other stakeholders are also taking an increasing interest in the ESG performance of their business partners.
At the same time, the so-called “value chain cap” limits the reporting requirements for companies with up to 1,000 employees, thereby reducing the “trickle-down effect” in the value chain: A company subject to reporting requirements may generally not require information from such a value-chain partner that goes beyond the scope of the relevant voluntary standard (VSME).
For SMEs, this means, on the one hand, that requests for ESG data should be proportionate, standardized, and transparent, and that continuous improvement in ESG performance should be ensured.
The process of a CSRD project
How does RiskSafe ESG Management GmbH provide support?
RiskSafe supports companies in Austria in the structured preparation and implementation of their sustainability reporting. Depending on the specific circumstances, this support may include, for example:
In any case, the specific service should be tailored to the company’s size, industry, corporate structure, data readiness, and reporting requirements.
What role do the ESRS play?
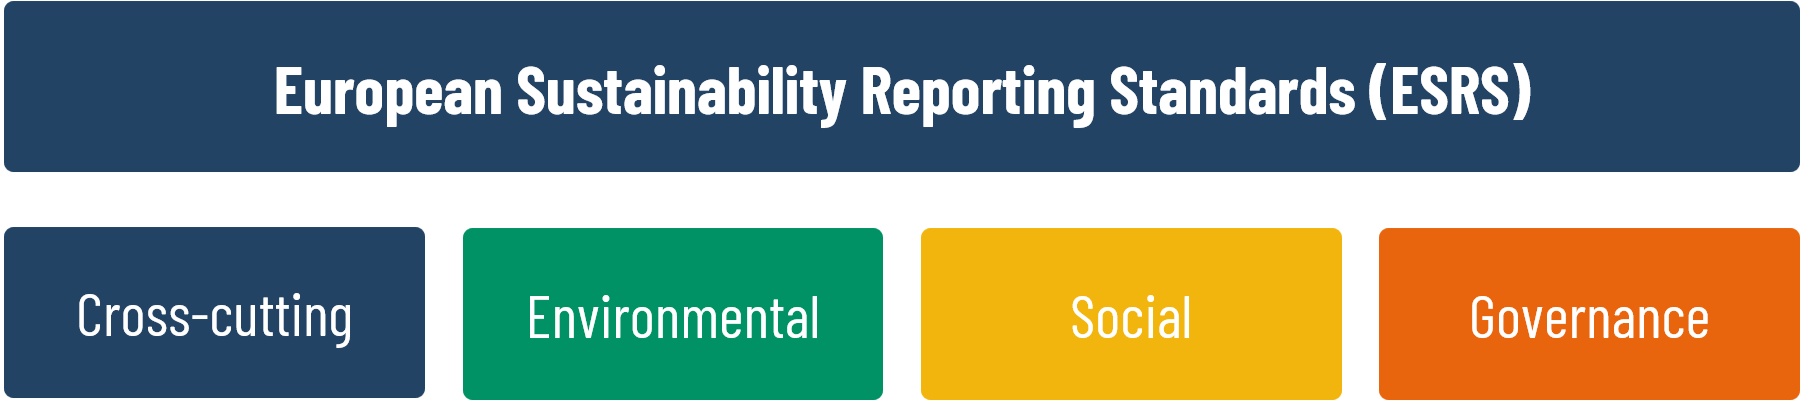
The European Sustainability Reporting Standards (ESRS) provide concrete guidance on the CSRD. They specify what sustainability information a company subject to reporting requirements must disclose in its sustainability statement. The ESRS combine three perspectives:
The ESRS are therefore not a voluntary ESG questionnaire. For companies within the mandatory scope of the CSRD, they constitute the binding reporting framework as soon as the applicable version takes legal effect.
Our offer
We help companies in Austria with the structured preparation and implementation of their sustainability reporting.
With our many years of experience in sustainability reporting, sustainability management, management systems, CO2 management, legal compliance, and as environmental verifiers, we are the ideal partner for you.
Request a free initial consultation.
An overview of the 12 ESRSs
The ESRS consist of two overarching standards and ten thematic standards:
General requirements
ESRS 1- Reporting principles
- Double materiality
- Value chain
- Time horizons
- Data quality and structure of the sustainability statement
Climate change
ESRS E1- Climate protection
- Adaptation to climate change
- Energy
- Greenhouse gas emissions
- Climate goals and transition plan
In-house staff
ESRS S1- Working Conditions
- Equal treatment, diversity
- Health and safety
- Compensation and social dialogue
Corporate governance
ESRS G1- Business ethics
- Corruption and bribery
- Lobbying
- Payment practices and supplier relationships
General information
ESRS 2- Governance
- Strategy
- Impact management
- Risks and opportunities
- Metrics and goals
Environmental pollution
ESRS E2- Air
- Water
- Floor
- Pollutants, substances of particular concern
- Measures to prevent or reduce pollution
Workers in the value chain
ESRS S2- Working Conditions
- Human rights
- Forced labor and child labor
- Further impacts on employees along the value chain
Water and marine resources*
ESRS E3- Water withdrawal
- Water consumption
- Discharges, as well as impacts and interdependencies related to water and marine resources
Affected communities
ESRS S3- Impact on communities
- Rights
- Participation
- Indigenous peoples
- Remedial measure
Biodiversity and ecosystems
ESRS E4- Locations
- Dependencies
- Impact
- Risks, Opportunities, and Measures for the Protection and Restoration of Biodiversity and ecosystems
Consumers and end users
ESRS S4- Health and safety
- Privacy
- Access to products and services
- Responsible marketing
- Impact on users
Resource use and the circular economy
ESRS E5- Inflows of resources
- Resource Use
- Waste
- Products
- Materials
- Circular Economy
An overview of the 12 ESRSs
The ESRS consist of two overarching standards and ten thematic standards:
(Click the boxes for more details)
CROSS-FUNCTIONAL
General requirements
ESRS 1- Reporting principles
- Double materiality
- Value chain
- Time horizons
- Data quality and structure of the sustainability statement
General information
ESRS 2- Governance
- Strategy
- Impact management
- Risks and opportunities
- Metrics and goals
ENVIRONMENT
Climate change
ESRS E1- Climate protection
- Adaptation to climate change
- Energy
- Greenhouse gas emissions
- Climate goals and transition plan
Environmental pollution
ESRS E2- Air
- Water
- Floor
- Pollutants, substances of particular concern
- Measures to prevent or reduce pollution
Water and marine resources
ESRS E3- Water withdrawal
- Water consumption
- Discharges, as well as impacts and interdependencies related to water and marine resources
Biodiversity and ecosystems
ESRS E4- Locations
- Dependencies
- Impact
- Risks, Opportunities, and Measures for the Protection and Restoration of Biodiversity and ecosystems
Resource use and circular economy
ESRS E5- Inflows of resources
- Resource Use
- Waste
- Products
- Materials
- Circular Economy
SOCIAL ISSUES
Own workforce
ESRS S1- Working Conditions
- Equal treatment, diversity
- Health and safety
- Compensation and social dialogue
Workers in the value chain
ESRS S2- Working Conditions
- Human rights
- Forced labor and child labor
- Further impacts on employees along the value chain
Affected communities
ESRS S3- Health and safety
- Privacy
- Access to products and services
- Responsible marketing
Consumers and end-users
ESRS S4- Health and safety
- Privacy
- Access to products and services
- Responsible marketing
- Impact on users
GOVERNANCE
Corporate governance
ESRS G1- Business ethics
- Corruption and bribery
- Lobbying
- Payment practices and supplier relationships
Which ESRS are relevant for a company?
Not every company is automatically required to disclose all information on every topic. Reporting follows the principle of double materiality:
- ESRS 1 and ESRS 2 form the general framework.
- The thematic standards E1 through E5, S1 through S4, and G1 are assessed for their impacts, risks, and opportunities.
- As a rule, only key topics are covered in sufficient depth.
- The decision regarding why a matter was classified as non-material must be documented in a way that is transparent.
Materiality assessment is therefore not a one-time workshop without follow-up processes. It must be integrated with strategy, risk management, stakeholder dialogue, the value chain, data processes, and reporting.
What’s new in the revised ESRS 2026?
On July 3, 2026, the European Commission adopted revised ESRS. The goal of the revision is to make sustainability reporting significantly more streamlined and clearer. According to the Commission …
- The standards will become shorter and clearer,
- The number of required data points is significantly reduced,
- Optional data points from the previous system are omitted,
- Repetitive information and narrative requirements are streamlined,
- Transitional and transitional relief provisions are clarified,
- The principle of double materiality remains a fundamental principle
The 2026 revised version retains the basic structure—with ESRS 1, ESRS 2, E1 through E5, S1 through S4, and G1—but organizes the requirements more closely around key topics and relevant data points. In practice, this does not mean that companies can dispense with a materiality analysis. On the contrary: the materiality analysis becomes even more important because it guides the selection of the information that is actually to be reported.
When do the revised ESRS take effect?
The European Commission adopted Delegated Act 2026/1563 on July 3, 2026. The revised ESRS will thus take legal effect on November 10, 2026.
According to the proposed implementation mechanism, the revised ESRS will generally apply to fiscal years beginning on or after January 1, 2027.
For companies that are already subject to reporting requirements, voluntary early adoption for the 2026 fiscal year is possible as soon as the delegated act enters into force. They must transparently disclose which option is being used for the sustainability report:
How many data points must be reported?
The previous version of the ESRS contained a very large number of quantitative and qualitative data points. The European Commission has adopted the 2026 revised version, which is intended to reduce the number of mandatory data points by more than 60 percent and the total number of data points by more than 70 percent.
However, a specific number should not be cited on the website as a universally applicable value. The information that is actually relevant depends, among other things, on:
The European Financial Reporting Advisory Group (EFRAG), which developed the ESRS as an expert organization on behalf of the Commission, is providing a new list of data points and a draft XBRL taxonomy as supporting materials for the revised versions. These materials assist with implementation but do not replace the binding delegated act and are not automatically a source of law in their own right.
What data must companies collect for the ESRS?
Reliable ESRS reporting typically requires data from several business units:
- Finance and controlling: revenue, investments, operating expenses, provisions, and financial impacts,
- Energy and the Environment: Energy consumption, emissions, water, waste, materials, biodiversity, and pollution,
- Human resources and occupational safety: workforce composition, working conditions, health, safety, diversity, and compensation,
- Purchasing and supply chain: suppliers, origin, risks, audits, and complaints,
- Legal and compliance: policies, incidents, corruption, whistleblower programs, and legal disputes,
- Risk management: physical and transient risks, opportunities, scenarios, and resilience,
- Management and supervisory bodies: responsibilities, authorities, incentive systems, and oversight.
For each key data point, the source, calculation method, time period, unit, responsibility, controls, and supporting documentation should be documented. Estimates and data gaps must be clearly identified and justified.
Frequently asked questions about CSRD reporting in Austria
Do you have any questions?
With our many years of experience, we are the ideal partner for you. We’d be happy to advise you and assist you in integrating ESG-related processes into your company. You’ll be surprised to find that, in addition to other benefits, this will even help you save money!
Last updated: October 10th, 2026 | Author: Hans Kitzweger, Dipl.-Ing., MBA

About the Author:
Hans Kitzweger is the Managing Director of RiskSafe ESG Management GmbH and a state-certified environmental auditor. A chemical engineer with an MBA, he has many years of experience in ESG and sustainability management, CO₂ accounting, decarbonization, environmental and occupational safety, management systems, compliance, and sustainability reporting. As the founder of RiskSafe, he helps companies integrate ESG requirements into their strategy, management, and reporting in a technically sound, legally compliant, and practical manner.